Is Financing a Greenhouse a Good Idea? 2026 Guide
Copy Link
Table of Contents
- Why Homeowners Finance a Greenhouse Instead of Paying Cash
- Greenhouse Financing Options: Rent to Own, Loans, and Cards
- The Cost of Building a Custom Greenhouse in Chester County
- The ROI of Backyard Greenhouses: What Buyers Actually Pay For
- Hidden Costs and Risks of Financing a Greenhouse
- How Riehl Structures Handles Greenhouse Financing and Delivery
- Conclusion: When Financing a Greenhouse Makes Sense
- Frequently Asked Questions
Last Updated: September 13, 2026
Why Homeowners Finance a Greenhouse Instead of Paying Cash
Financing a greenhouse is a good idea when the structure will be used for years and the monthly payment fits comfortably within your budget; it becomes a poor idea when the loan stretches past the useful life of the structure or carries a prepayment penalty. At Riehl Structures, we’ve helped customers in West Chester, PA with this exact question for over 30 years.
The cash-versus-financing decision usually comes down to three things: how much of your savings you want to tie up, whether you can wait through a savings period, and whether the greenhouse will pay for itself through extended growing seasons or added property value.
A custom greenhouse is a long-term purchase, not an impulse buy. Most buyers keep their structure for a decade or more, which changes the math considerably. Spreading the cost over several years often makes more sense than draining an emergency fund (consumer.ftc.gov).
Financing makes sense when the greenhouse’s useful life clearly outlasts the repayment period. If you’re financing over five years, you should expect to use the structure well beyond that.
Greenhouse Financing Options: Rent to Own, Loans, and Cards
Greenhouse financing options generally fall into three categories: rent-to-own agreements, personal loans, and credit cards. Each carries different terms, approval requirements, and total costs, so matching the option to your situation matters more than chasing the lowest advertised rate.
| Option | Approval Difficulty | Best For | Main Trade-off |
|---|---|---|---|
| Rent-to-own | Low | Buyers with limited credit history | Higher total cost if paid slowly |
| Personal loan | Moderate | Buyers who want fixed terms | Requires decent credit |
| Credit card | Easy | Short-term, small balances | High interest if carried |
| Home equity | Moderate | Large projects, low rates | Puts your home at risk |
Rent-to-Own Agreements
Rent-to-own lets you take possession of a greenhouse while making installment payments, with ownership transferring once the balance is paid. Approval tends to be easier than a bank loan because the structure itself serves as collateral.
The catch is total cost. A common mistake is focusing on the monthly payment and ignoring how much the structure costs by the time you finish paying. Ask two questions before signing: what’s the total payoff amount, and is there a prepayment penalty? Riehl Structures offers rent-to-own with no prepayment penalties, so paying off early costs you nothing extra.
Personal Loans and Credit Cards
Personal loans give you a fixed interest rate and a set repayment schedule, which makes budgeting straightforward. Credit cards work for smaller purchases you can pay off quickly, but carrying a balance month to month gets expensive fast.
For most buyers financing a greenhouse, a personal loan beats a credit card unless you can clear the balance within a billing cycle or two. Neither option requires home equity, which keeps your house out of the equation entirely.
The Cost of Building a Custom Greenhouse in Chester County
The cost of building a custom greenhouse depends on size, materials, foundation requirements, and site conditions, so no single figure applies to every property. Pricing depends on these factors, so two greenhouses of identical footprint can differ substantially in price if one sits on level ground and the other needs site work.
Here’s what actually drives the number up or down:
- Size and footprint: Larger structures use more materials and may need a poured foundation.
- Glazing material: Glass, polycarbonate, and twin-wall panels carry different costs and insulation values.
- Site preparation: Sloped or uneven yards often need grading or a retaining base.
- Foundation type: A gravel pad costs less than a concrete slab.
- Custom features: Ventilation, shelving, heating, and water access add to the base price.
Because pricing varies this much, the honest answer is that you need a quote based on your specific yard. Riehl Structures provides free quotes and free delivery within 30 miles of its West Chester and King of Prussia locations, so you can get a real number without committing.
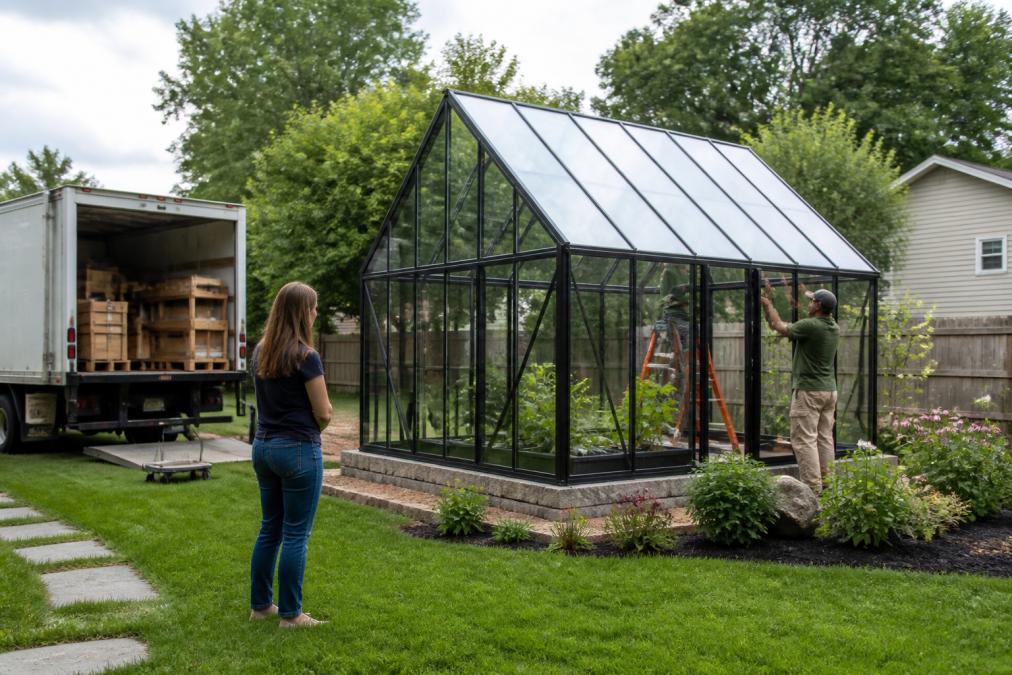
Professional installation ensures the structural integrity of your investment, but long-term success ultimately depends on the consistent practices outlined in our greenhouse management guide.
The ROI of Backyard Greenhouses: What Buyers Actually Pay For
The ROI of backyard greenhouses rarely shows up as a dollar figure on a spreadsheet. It can show up as extended growing seasons, food savings, and a structure that appeals to buyers when you eventually sell.
Buyers often look for greenhouses that look permanent and well-built. A flimsy kit greenhouse may add little to a property’s appeal, while a solid, Amish-built structure can read as a genuine feature. That’s a practical difference between a greenhouse that holds value and one that doesn’t.
The other return is harder to quantify but just as real: a greenhouse can let you start seedlings earlier and keep growing later, which matters in southeastern Pennsylvania’s climate. For gardeners who sell at local markets or simply want year-round produce, that extended season can be a significant benefit.
If resale value matters to you, prioritize a permanent foundation and quality glazing. Buyers can tell the difference between a greenhouse built to last and one assembled from a kit, and it affects what they’re willing to pay.
Hidden Costs and Risks of Financing a Greenhouse
The hidden costs of financing a greenhouse are what can catch buyers off guard. Interest charges, prepayment penalties, and insurance requirements can all add to the total, and none of them may appear in the advertised monthly payment.
Watch for these specific risks:
- Prepayment penalties: Some lenders charge a fee for paying off early, which traps you in the loan even when you have the cash.
- Deferred interest promotions: Store cards often advertise “no interest if paid in full,” then retroactively charge interest on the whole balance if you miss the deadline.
- Home equity risk: Using a home equity loan or line of credit puts your house on the line if you fall behind (consumerfinance.gov).
- Underinsurance: Many homeowners don’t realize their policy may not cover an outdoor structure until they file a claim.
The biggest mistake is treating financing as free money. It isn’t. The question isn’t whether you can afford the monthly payment; it’s whether the total cost, including interest, still makes sense for what you’re getting.
How Riehl Structures Handles Greenhouse Financing and Delivery
Riehl Structures offers flexible financing options, including Rent to Own, with no prepayment penalties and no home equity required. That means you can pay off your greenhouse early without a fee, and you never have to put your house up as collateral.
The process is designed to be turnkey. Here’s how it works:
- Free consultation and quote: You describe your yard, goals, and budget, and receive a custom quote.
- Financing selection: Choose rent-to-own or another option based on your situation.
- Custom design: The greenhouse is built to your specifications, not pulled off a shelf.
- Free delivery within 30 miles: Delivery covers West Chester, King of Prussia, and the surrounding area.
- Installation: The structure is placed and set up on your property, not dropped in the driveway.
That last point matters more than people expect. A common frustration with cheap online sellers is a structure left curbside with no setup. Riehl Structures handles delivery and placement as part of the process.
Conclusion: When Financing a Greenhouse Makes Sense
Financing a greenhouse makes sense when the structure will serve you for years, the payment fits your budget, and the terms carry no penalties for paying early. It makes less sense when the loan outlasts the greenhouse or ties up your home equity.
If you’re a homeowner in the greater Philadelphia area weighing a custom greenhouse, Riehl Structures offers Amish-built quality, custom design, rent-to-own financing with no prepayment penalties, and free delivery within 30 miles of its West Chester and King of Prussia locations. Our team has spent over 30 years helping local families build backyards worth staying in.
Get a quote now and find out what a greenhouse built for your yard, and your budget, actually looks like.
Frequently Asked Questions
What are the benefits of financing a custom greenhouse?
Financing spreads the cost of a custom greenhouse into predictable monthly payments, so you can start growing sooner instead of waiting years to save the full amount. It also preserves your cash reserves for site preparation, raised beds, or irrigation. Many agreements, including rent-to-own, require no home equity, and some let you pay off early without a penalty. Compare the total cost of any greenhouse financing options against the sticker price before signing.
Is it better to save up or finance a backyard structure?
Saving up avoids interest and keeps your total cost at the sticker price. Financing makes sense when you want the structure now, the monthly payment fits your budget, and you plan to stay in the home long enough to use it. If you expect to move within two or three years, run the numbers on the ROI of backyard greenhouses first. A short payoff window with no prepayment penalty gives you the most flexibility either way.
Do Amish-built greenhouses hold their value?
Well-built greenhouses tend to hold value better than mass-market kits because the materials and joinery last longer. Buyers often pay attention to frame quality, glazing, and how the structure was anchored. A greenhouse that is permitted, properly sited, and in good condition is easier to sell with the home. Ask for the build details and keep your paperwork so you can show a future buyer what went into it.
What financing options are available for outdoor structures in Pennsylvania?
Common greenhouse financing options include rent-to-own agreements, personal loans from a bank or credit union, and credit cards. Rent-to-own usually requires no home equity and no prepayment penalty, which suits buyers who want a simple approval process. Personal loans may offer lower rates if your credit is strong. Ask each lender about the total cost over the full term, not just the monthly payment, before you commit.

Copy Link